A score is only one piece of the picture
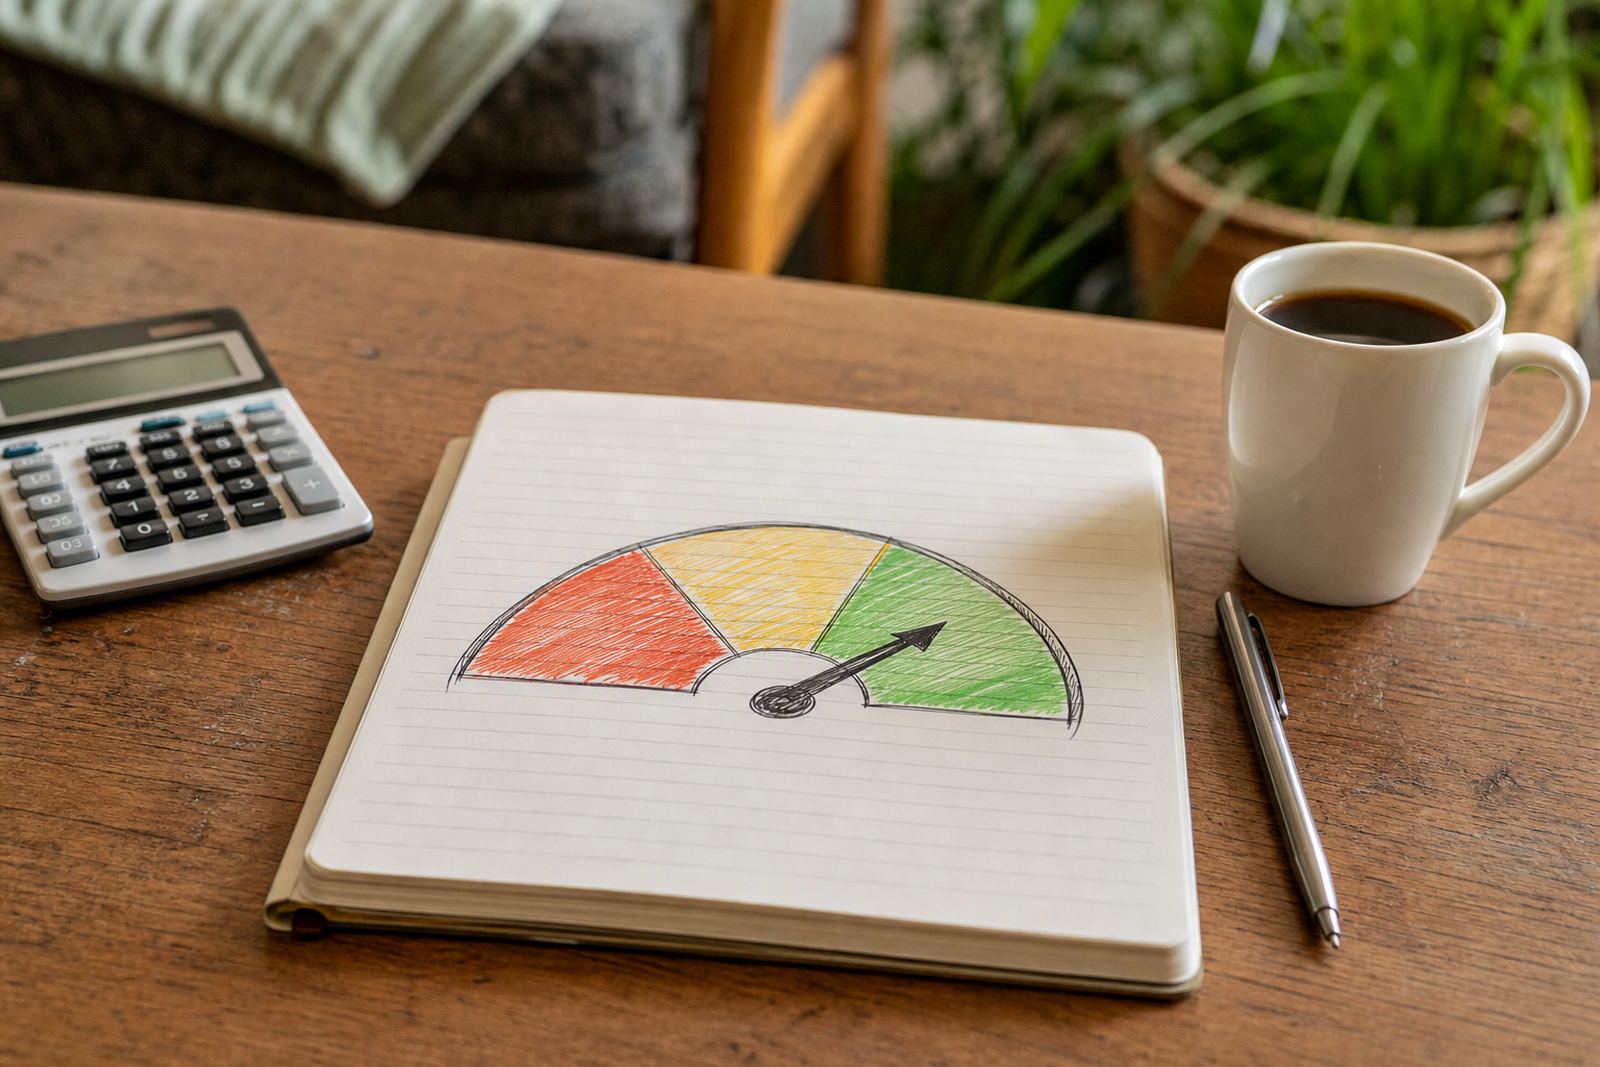
A credit score is a summary number tied to your credit history. Lenders may use it to get a fast view of risk, then they check the full credit report for context. In South Africa, that report can include accounts, payment patterns, defaults, judgments, and other records that credit providers are allowed to consider under the National Credit Act.
The number itself is not magic. A score can move because an account was paid late, a balance climbed, or a new credit line was opened. Different lenders may use different scoring models, so one score does not tell the whole story.
For many people, the useful question is not only “what is my score?” It is also “what information sits behind it?” That is where the report matters.
What lenders usually look for in the report
A credit report is a record pulled from a credit studio. It helps show how credit was used over time. A lender may read it alongside an application form, payslip details, bank statements, and affordability checks. The score gives a snapshot, but the report gives the reasons behind it.
- Payment history on current and past accounts
- Outstanding balances and instalment levels
- Defaults, judgments, and collections records
- Recent applications for credit
- Closed accounts that still appear on file
Someone in Rosebank may have the same score as a person in Durban yet have a very different report. One may have a thin file with few accounts. The other may have several accounts and a few missed payments. The number can look similar while the risk picture is not.
Why the National Credit Act matters
The National Credit Act sets rules for responsible lending and consumer protection. It is part of the framework that shapes how credit providers assess affordability and how debt review works. If a person feels overloaded by debt, the Act is one of the key legal references that registered debt counsellors use when guiding consumers.
It also matters because consumers have rights around access to information, fair treatment, and accurate records. If a report shows something that looks wrong, the next step is to check the source of the record and follow the dispute process. OpenCredit can explain the basics, but legal questions should be confirmed with a registered debt counsellor or the National Credit Regulator.
That matters in practical terms. A score can drop for reasons that are technical rather than dramatic, and the Act gives a structure for understanding what happens next.
Debt review changes the way credit is viewed
Debt review is a formal process for consumers who may be over-indebted. A registered debt counsellor looks at the full debt picture, assesses affordability, and may help propose a repayment plan through the proper legal route. It is not a casual budget chat. It has rules, documents, and consequences that should be understood before any decision is made.
People often ask how debt review links to a score. The short answer is that it is a separate legal process, but it can influence how credit is assessed while it is active. It is one reason people should check the details properly before acting. Never rely on a social media clip or a quick message thread for this part.
- Debt review is guided by the National Credit Act
- A registered counsellor must assess the application
- Documents such as ID, income proof, and expenses are usually needed
- The budget is central to the process
- The effect on future credit access must be understood clearly
For anyone in Sandton, Midrand, Pretoria, or elsewhere in Gauteng, the legal structure is the same. The rules do not change because the branch area changes.
Budgeting shows lenders how pressure builds
Budgeting is not just about writing down expenses. It shows whether income can cover essentials, debt instalments, and ordinary monthly life. Lenders look for signs that a person can pay without falling behind. If the budget is tight, the score may not explain the whole problem.
A useful budget lists rent or bond, transport, groceries, school costs, insurance, and debt repayments. Many households also deal with rising utility charges and transport costs, which can shift the picture quickly. In a city like Johannesburg, where fuel and commuting costs can press hard, a budget often needs more than a rough estimate.
When a budget is honest and complete, it becomes easier to see whether a small change or a formal debt process is more suitable. That judgment should be made with proper guidance, not guesswork.
A Rosebank example that feels familiar
Picture a working parent in Rosebank who checks a credit score online after being turned down for a store account. The score is lower than expected, but the report shows two late payments, one old collection account, and a recent credit application trail. None of that is unusual on its own, yet together it can explain the decision.
If the same person then reviews the budget, the problem may turn out to be a month-to-month gap rather than one bad event. That is where education helps. A score is a signal, not a verdict. The report, the budget, and the legal context all need to sit together.
People in Johannesburg, Pretoria, Cape Town, Durban, and Gqeberha often ask similar questions. What does the number mean? Why did it shift? Is debt review the right path? The answer depends on the facts and, where needed, advice from a registered debt counsellor or the National Credit Regulator.
Questions worth asking before you act
Before taking the next step, it helps to ask a few plain questions. These are not shortcuts, but they keep the discussion grounded in facts.
- What does the credit report actually show?
- Are there missed payments, judgments, or defaults?
- Has the debt been checked against the budget?
- Does the situation call for a registered debt counsellor?
- Should the National Credit Regulator be consulted on the legal side?
OpenCredit focuses on helping South Africans understand credit scores and debt review basics in clear language. That education can make the next conversation more useful, especially when the paperwork feels thick and the terms feel technical. A score is only one number, but it can open the door to a more informed discussion.